
The next step after the FAFSA
A practical guide to the numbers, questions, and tradeoffs that can help you choose your next step.
Learning how to compare financial aid offers can help you understand what college will really cost. A bigger award doesn’t automatically mean a more affordable school. What matters is the full cost, the type of aid, and a realistic plan for what’s left.
Use this guide whether you’re comparing colleges for the first time or reviewing costs for another year. Graduate students can follow the same process, with extra attention to fellowships, assistantships, and program length.
1. FAFSA submitted? Check these next.
Once your FAFSA is processed, review your FAFSA Submission Summary in your StudentAid.gov account. Check your answers and the “Next Steps” tab, then watch each school’s portal and email for document requests.
Your summary and your offer do different jobs.
The summary includes your Student Aid Index (SAI) and estimated eligibility. The SAI is not your bill. Each school provides its own financial aid offer; timing varies, so ask when yours will be available.
Confirm that each school has what it needs, including any separate aid applications or verification documents. Keep a list of financial aid, scholarship, housing, and enrollment deadlines.
2. Sort the offer into three buckets.
Aid offers use different layouts and labels. Identify each item before adding up the total.
Grants & scholarships
Generally don’t need to be repaid if you meet their terms. Check enrollment, eligibility, and renewal conditions.
Work-study
Money earned through an eligible job. A work-study award doesn’t guarantee a job or provide upfront cash for your bill.
Loans
Borrowed money, generally repaid with interest. Identify who borrows and review interest rates, fees, and repayment terms.
You can ask to accept less loan money than offered. Don’t assume a loan listed in the package is required.
3. Compare the same costs, for the same year.
Use each school’s full cost of attendance for your intended housing and enrollment plans. Include tuition, fees, housing, food, books, supplies, transportation, and personal expenses.
Some expenses are billed by the school; others are costs you’ll pay separately. Adjust estimates for your situation without counting the same expense twice.
Full annual cost − grants & scholarships = net price
Keep loans and work-study out of this subtraction. They help explain how you might cover costs; they don’t reduce the price.
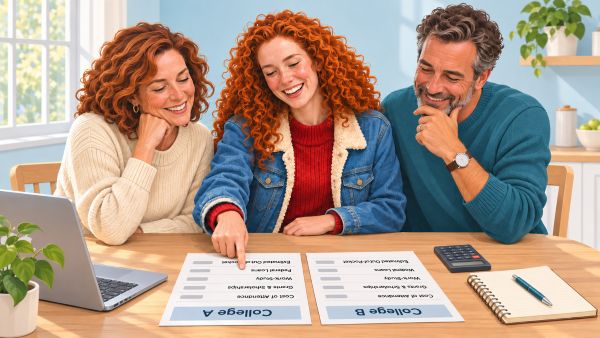
Illustrative example: Hypothetical costs and awards for one academic year.
| One academic year | College A | College B |
|---|---|---|
| Full estimated cost | $32,000 | $43,000 |
| Grants & scholarships | − $14,000 | − $20,000 |
| Net price | $18,000 | $23,000 |
College B offers more grant and scholarship money, but College A’s net price is $5,000 lower. The remaining amount isn’t automatically your loan amount: it’s what your funding plan still needs to address.
4. Ask what happens after the first year.
A first-year discount may not last through graduation. Estimate the cost of your full program, allowing for potential tuition and living-cost increases and changes in aid.
Questions worth asking
- Which awards renew, for how many terms, and at what amount?
- What GPA, credits, enrollment level, or annual application is required?
- What happens if I change majors, transfer, or need more time?
- Are housing, required equipment, clinical placements, or travel costs likely to change?
- For graduate programs: is funding guaranteed, and what tuition, fees, insurance, work hours, and summer support does it cover?
If borrowing is part of the plan, estimate total debt through graduation and a monthly payment using current loan terms. Compare that payment with a realistic starting-income budget, including rent, transportation, food, and other obligations.
Review current federal loan options and protections before comparing private loans. Check eligibility and limits for your program and year. For any loan, understand the interest rate, fees, repayment start date, and whether a parent or cosigner is taking on responsibility.
5. If the numbers don’t work yet, ask for help.
Start with the financial aid office. Ask about additional institutional aid, available scholarships, and the school’s aid review process.
If your family has experienced job loss, reduced income, or significant expenses that aren’t reflected in the FAFSA, ask about a special-circumstances review and required documentation. An increase isn’t guaranteed.
- Keep applying for scholarships. Ask how outside awards could affect other aid before counting on the full amount.
- Budget work income carefully. Consider realistic hours, job availability, and when you’ll actually receive pay.
- Ask about payment plans. Check fees and due dates. Spreading payments out doesn’t reduce the total cost.
- Explore a lower-cost path. Compare commuting, different housing, another school, or a transfer route. Confirm credit transfer and time to degree.
A question you can copy
“I’m reviewing my aid offer and estimate that I still need to cover $___ for the year. Can you help me confirm my costs, explain renewal requirements, and identify any additional aid or review options?”
Need help covering costs sooner?
Visit our Need Money ASAP? page for guidance on contacting your financial aid office, finding campus support, exploring payment plans, and requesting an aid appeal.
6. Weigh affordability alongside fit.
Cost matters, and so does having the support to complete your program. Compare academic programs, course availability, advising, accessibility services, tutoring, career support, location, and your sense of belonging.
Ask about graduation rates, typical time to finish, and outcomes for your intended program. For transfer pathways, verify which credits apply to your degree. A lower annual price can become more expensive if finishing takes longer.
Make sure the plan works beyond the first semester.
Discuss what you or your family can contribute each year without putting essential expenses at risk. Build a small cushion for unexpected costs, and consider how the plan would hold up if your expenses or income changed.
Before you say yes
✓ I compared full costs for the same academic year and enrollment plans.
✓ I separated grants and scholarships from work-study and loans.
✓ I checked renewal requirements and estimated costs through graduation.
✓ I have a realistic plan for the remaining costs and any borrowing.
✓ I asked about missing information, aid reviews, and unresolved questions.
✓ I confirmed deposit, housing, aid acceptance, and refund deadlines.
Follow the school’s instructions to accept the aid you want and complete any required steps.
If an offer is delayed, ask about a decision or deposit extension before the deadline; don’t assume one is automatic.
Keep scholarships in your plan
Your search can keep going.
Explore your scholarship matches on Red Kite as you plan for college, continue your degree, or prepare for graduate school.
Explore my matches →Sources & helpful tools
- Federal Student Aid: After submitting your FAFSA
- Federal Student Aid: Evaluate your aid offers
- Federal Student Aid: Understand your Submission Summary
- Federal Student Aid: Aid terms and special circumstances
- Federal Student Aid: Loan Simulator
Guidance reviewed November 17, 2026. Confirm current aid and loan terms with your financial aid office and official program resources.